Finance Your Home Renovation With Confidence
Planning to purchase or renovate a home using an FHA 203(k) loan? Precision Remodeling provides professional residential renovation services designed to help homeowners complete qualifying improvement projects with quality workmanship and clear project coordination.
From kitchens and bathrooms to major home improvements, our team can help bring your renovation plans to life.
Our 203(k) Renovation Services
Residential Renovations for FHA 203(k) Projects
For Smaller Residential Improvements
Limited 203(k)
Designed primarily for less extensive repairs and non-structural improvements.
Examples:
- Kitchen updates
- Bathroom updates
- Flooring
- Painting
- Doors and windows
- Minor property repairs
For Larger Renovation Projects
Standard 203(k)
Designed for more extensive rehabilitation and projects that may include major or structural work.
Examples:
- Major renovations
- Structural repairs
- Extensive property rehabilitation
- Larger remodeling scopes
- Major system upgrades
How It Works
How Your 203(k) Renovation Project Works
Why Choose Precision Remodeling?
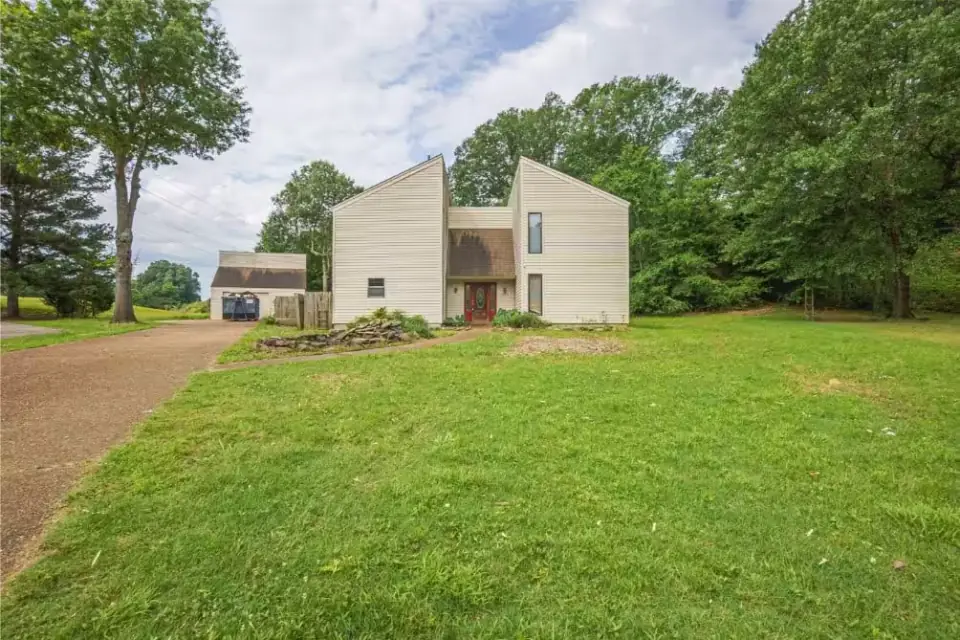
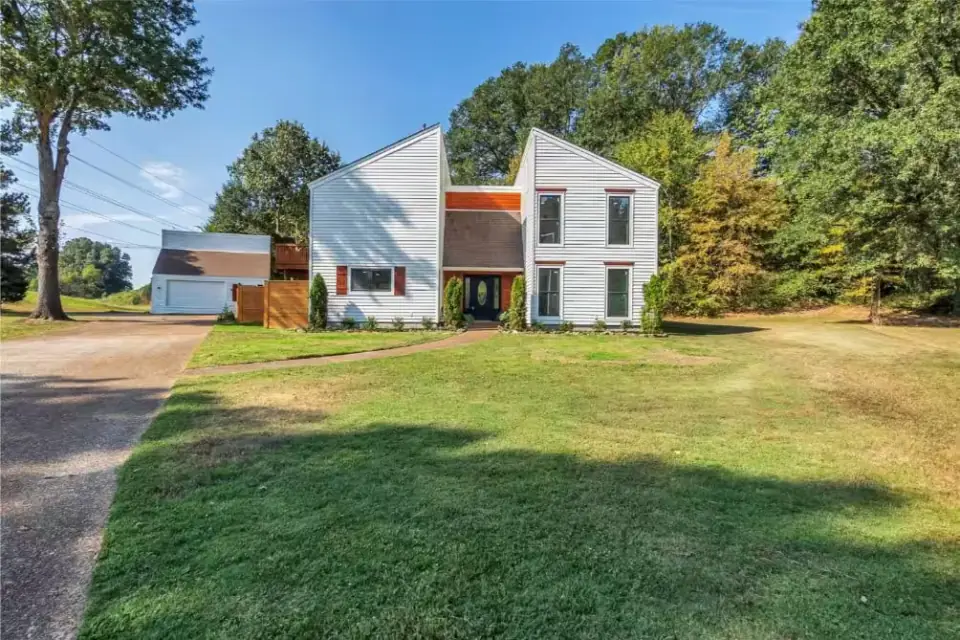
Project Gallery
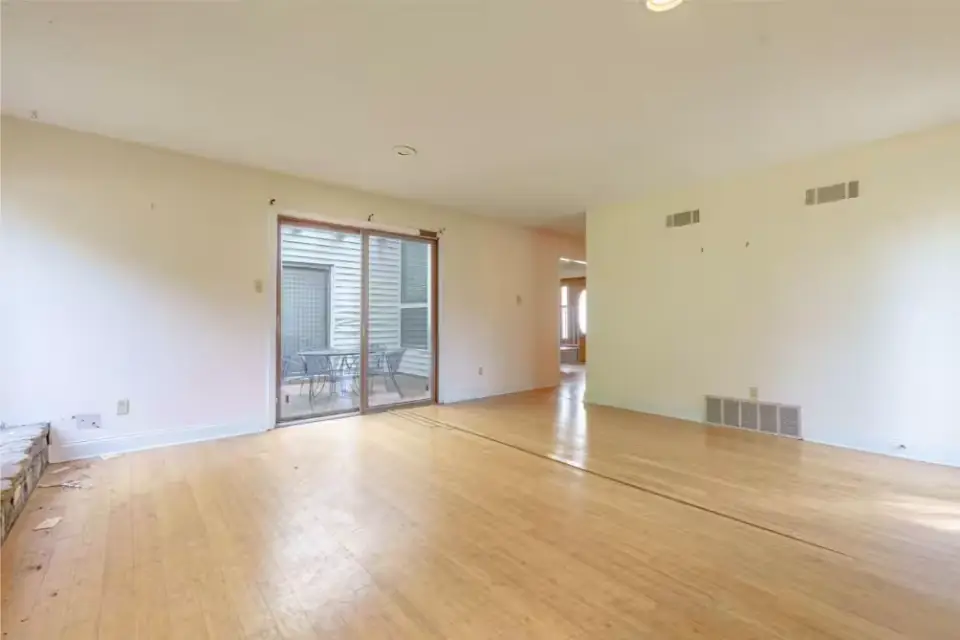
Imagine What's Possible
FHA 203(k) Contractor in Memphis & Germantown, TN Turn a Fixer-Upper Into a Home You Actually Love
A house with good bones and outdated everything else can be a genuinely great deal, if you can afford both the purchase and the renovation. That’s exactly the gap an FHA 203(k) loan is built to close, and it’s exactly where the right FHA 203(k) contractor makes or breaks the whole project.
This page walks through what a 203(k) contractor actually is, how the loan process works alongside the renovation, and what separates a contractor who keeps your draws moving on schedule from one who quietly slows everything down.
What Is an FHA 203(k) Contractor?
A 203k contractor is a licensed general contractor who works within the specific requirements of the FHA 203(k) renovation loan program, a loan that lets homebuyers finance both the purchase price of a home and the cost of renovating it, rolled into a single mortgage. Unlike a typical remodeling project paid out of pocket, a 203(k) project is tied directly to loan draws, inspections, and paperwork requirements set by the lender and HUD.
This matters because the contractor isn’t just building, they’re also responsible for submitting accurate cost estimates, staying within approved scope, and completing work on the timeline the loan requires.
How Does an FHA 203(k) Loan Actually Work?
An FHA 203(k) loan wraps the purchase price and renovation cost into one mortgage, based on the home’s projected value after the work is complete, not its current, as-is condition. Funds for the renovation aren’t handed over all at once; they’re held in an escrow account and released in draws as work is completed and verified by inspection.
According to HUD’s official 203(k) program overview, this structure exists specifically to protect both the lender and the homeowner, ensuring renovation funds are actually spent on completing the approved work.
Standard vs. Limited 203(k), Which Loan Fits Your Project?
Not every 203(k) loan works the same way. The two main versions differ significantly in scope:
- Limited 203(k): Covers non-structural repairs and cosmetic updates, kitchens, bathrooms, flooring, painting, typically capped at a lower total renovation budget and without a required consultant.
- Standard 203(k): Covers larger projects, including structural repairs, room additions, and major system replacements, and requires a HUD-approved consultant to oversee the process alongside the contractor.
Knowing which category your project falls into shapes almost everything else, the paperwork required, the timeline, and which contractors are even eligible to bid the work.
What Makes a Contractor “203k Certified”?
There’s no single national “203k certification exam” the way there is for some trades, instead, being 203k certified in practice means a contractor understands the program’s specific requirements: how draws work, how to submit a compliant cost estimate (“specification of repairs”), and how to work alongside a HUD consultant when one is required. Many lenders also maintain an approved contractor list, and being on it typically requires proof of licensing, insurance, and sometimes prior 203(k) project experience.
A 203k general contractor who’s done this before will move your project through inspections and draws far more smoothly than one encountering the paperwork for the first time.
What to Look for in a 203k Licensed Contractor
Before hiring any 203k contractor near me, confirm:
- Active general contractor licensing and insurance in your state
- Direct experience with 203(k) draws and inspections, not just general remodeling
- Comfort working alongside a HUD consultant, if your loan is a Standard 203(k)
- A detailed, compliant written estimate that matches what the lender requires for approval
- A realistic project timeline that accounts for inspection and draw scheduling, not just construction time
A 203k licensed contractor who can’t speak comfortably about draws, consultants, or HUD specifications probably hasn’t done many of these projects, and this isn’t the loan type to learn on.
The 203(k) Renovation Process, Step by Step
- Loan approval and scope definition — working with your lender (and consultant, if Standard 203(k)) to define approved renovation scope
- Contractor bid and specification of repairs — a detailed, compliant cost breakdown submitted for lender approval
- Closing and escrow setup — renovation funds held in a dedicated account
- Construction begins — work proceeds according to the approved scope and timeline
- Draw inspections — completed work is verified before each portion of funds is released
- Final inspection and project closeout — remaining funds released once work is fully complete
Every step depends on the one before it moving smoothly, which is exactly why contractor experience with this specific process matters so much.
How to Finance Your Home Renovation With a 203(k) Loan
If you’re trying to finance your home renovation and don’t have significant cash reserves, a 203(k) loan is one of the more accessible paths, especially for buyers purchasing a home that needs work as a condition of financing at all, some lenders won’t approve a mortgage on a home in poor condition without a renovation plan attached. The process starts with your lender, not your contractor, but choosing a contractor experienced in this program early, even before your offer is accepted, can meaningfully speed up the rest of the process.
Common Mistakes Homeowners Make With 203(k) Projects
A few recurring issues tend to slow down or derail 203(k) projects:
- Underestimating the timeline — draw inspections add real time compared to a typical cash-paid renovation
- Choosing a contractor unfamiliar with the program — leading to rejected specifications and delayed draws
- Scope creep mid-project — changes outside the originally approved specification often require re-approval, which pauses funding
- Not budgeting a contingency reserve — many 203(k) loans require one, and unexpected issues (especially in older homes) are common
Working with a fha 203k general contractor who’s navigated these issues before is the single biggest factor in avoiding them yourself.
Why Choosing the Right 203(k) General Contractor Matters
The contractor you choose affects more than construction quality on a 203(k) project, they directly affect whether your draws release on time, whether your loan timeline holds, and whether inspections go smoothly. An inexperienced contractor can genuinely stall a project for weeks over paperwork issues that an experienced fha 203 k contractor would have avoided from the start.
Precision Remodeling has guided Memphis and Germantown homeowners through the 203(k) process for over a decade, working directly with lenders and consultants to keep draws, inspections, and construction moving together instead of against each other. If you want the full walkthrough of how to vet a contractor for this specific loan type, our in-depth FHA 203k Contractor Guide covers the vetting process in more detail.
203(k) Contractor Services Near Memphis & Germantown
If you’re comparing a 203k contractor near me or 203k general contractor near me, here’s what sets Precision Remodeling apart:
- 10+ years of hands-on renovation experience, including 203(k) projects specifically
- Licensed and insured general contracting in Tennessee
- Direct experience with lender draw requirements and HUD consultant coordination
- Transparent, compliant written estimates built for loan approval, not just internal budgeting
- A track record of 200+ completed projects across the Memphis metro, viewable on our projects page
Areas We Serve
We provide fha 203k contractor services throughout:
Memphis, TN · Germantown, TN · Collierville, TN · Bartlett, TN · Eads, TN · Somerville, TN · Atoka, TN · Brighton, TN · Munford, TN · Millington, TN · Southaven, MS · Olive Branch, MS
Don’t see your city listed? Reach out directly, we cover a wider radius on request.
Conclusion
A 203(k) loan can turn a home other buyers pass on into exactly the house you actually want, but only if the renovation side of the process runs as smoothly as the financing side. That’s almost entirely a function of who you hire, not luck.
Precision Remodeling has guided Memphis and Germantown homeowners through the FHA 203(k) process for over a decade, working directly with lenders and consultants so your draws, inspections, and construction timeline actually stay in sync. One experienced team, from the first specification to the final inspection.
Considering a 203(k) renovation loan? Call 901-519-3747 or schedule a free project consultation today. We’ll walk you through exactly what your loan type requires, before you’re already locked into a timeline.